Backtest
Test the market before you trade the market
Pressure-test any options strategy against more than a decade of real, minute-by-minute market data — and see how it behaved historically before you put capital at risk.
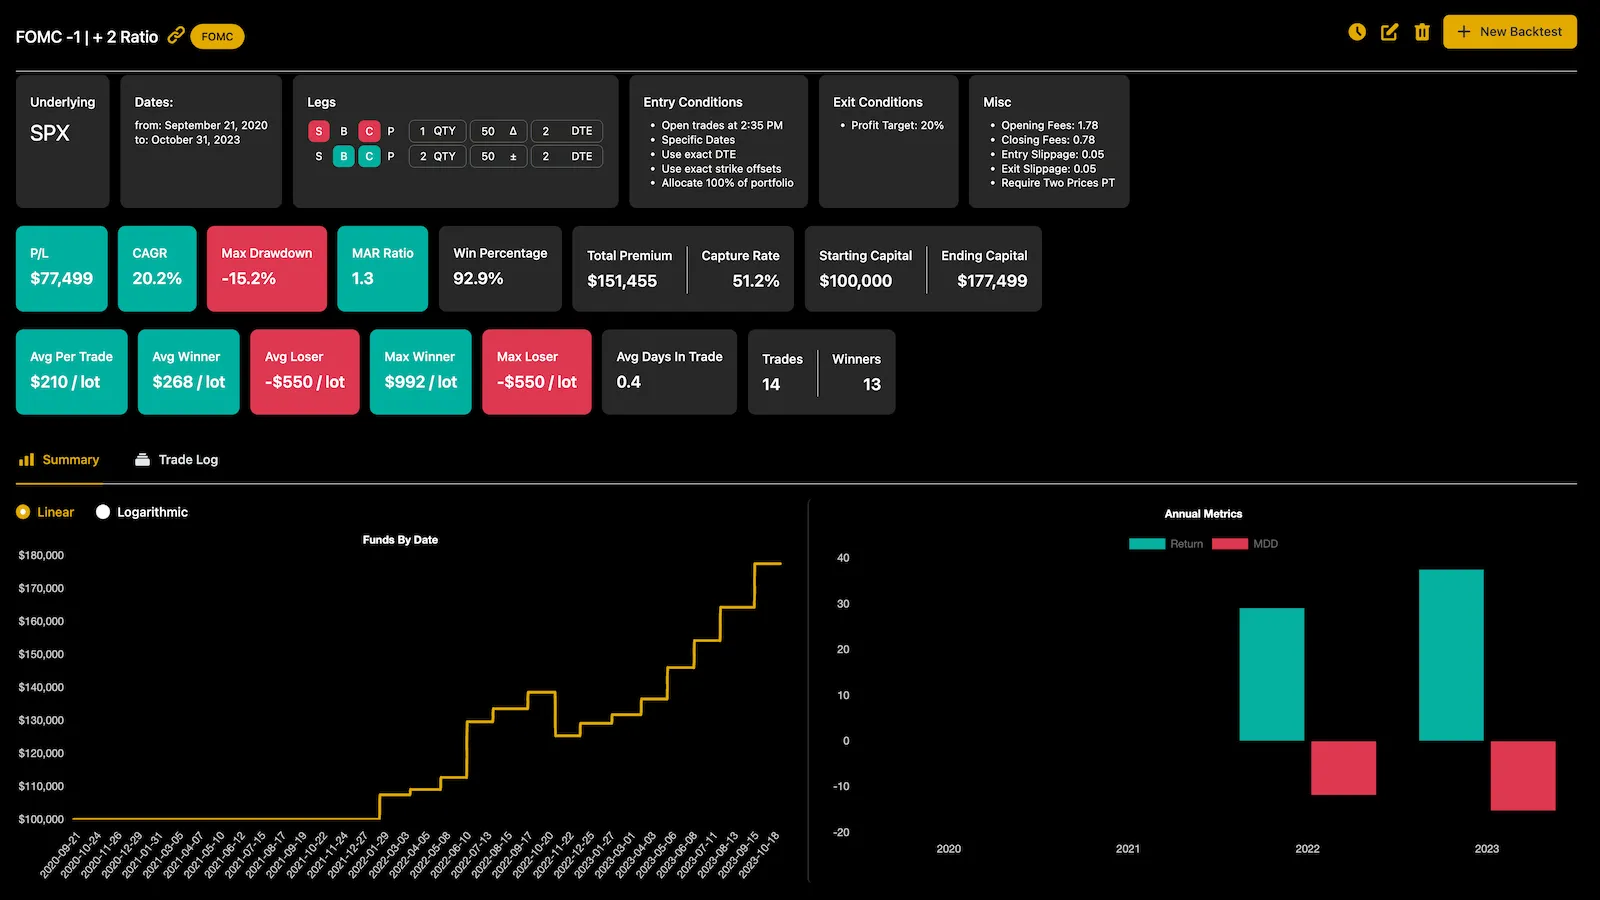
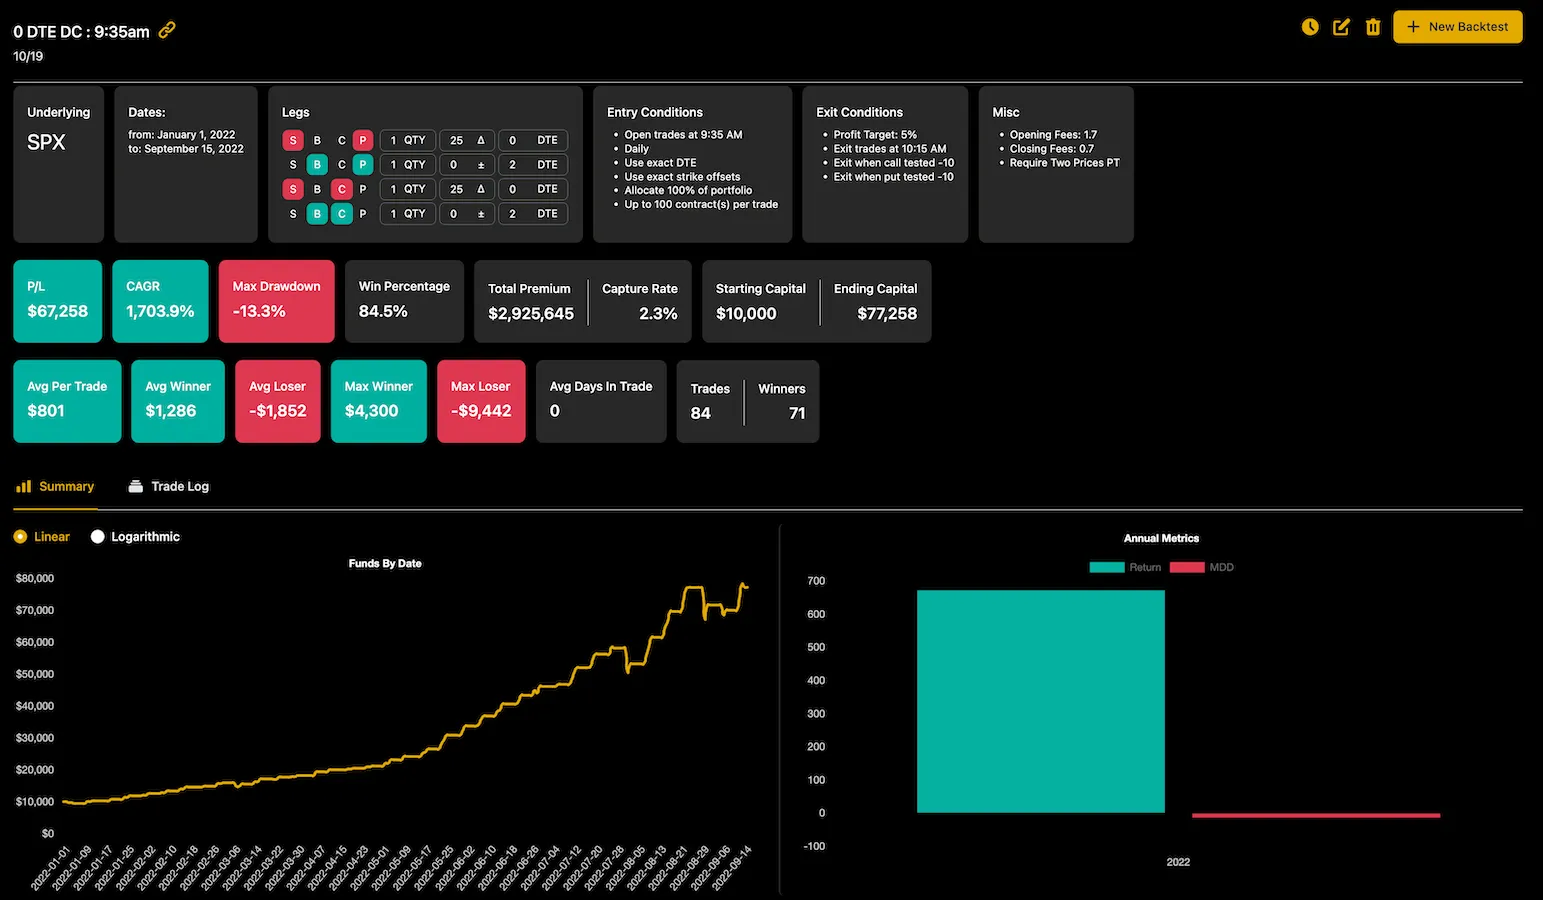
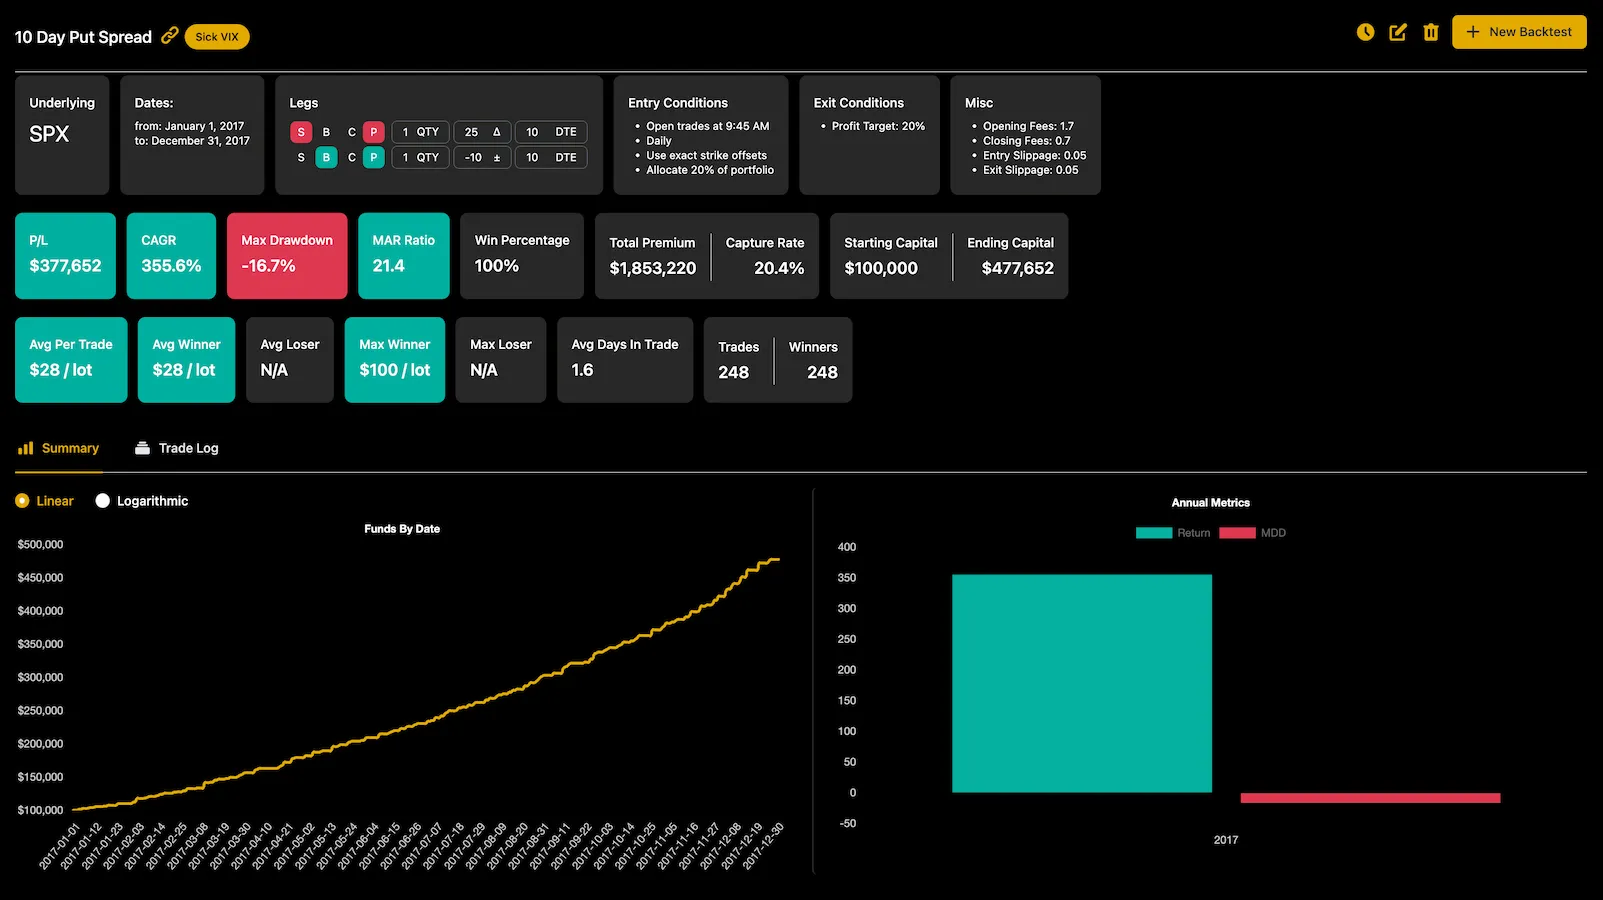
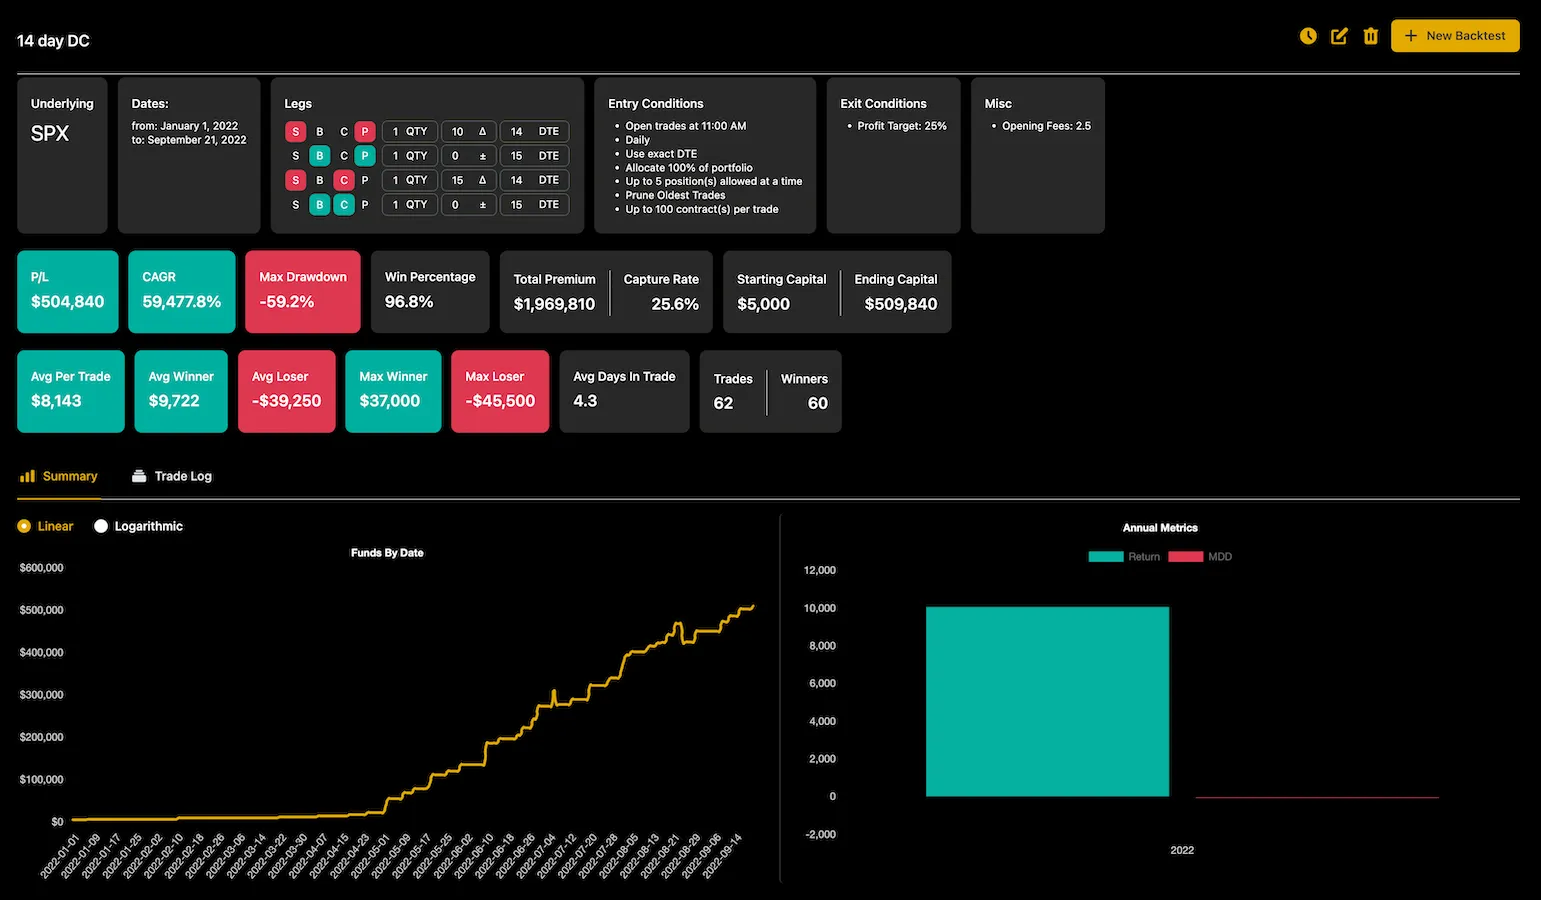
Strong enough for a hedge fund, made for retail traders
From a simple long call to a broken-wing butterfly, build it in seconds with 16 ready-made templates or design your own from scratch — then test it against more than a decade of real market data.
- Real market data
- Every fill comes from recorded market quotes, not a pricing model, going back to January 2013
- Up to 8 legs
- Spreads, condors, flies, calendars, ratios, lizards — if you can trade it, you can test it
- Blazing fast
- Years of market data crunched in seconds, so you can iterate instead of waiting
Trade 0DTE? We built this for you
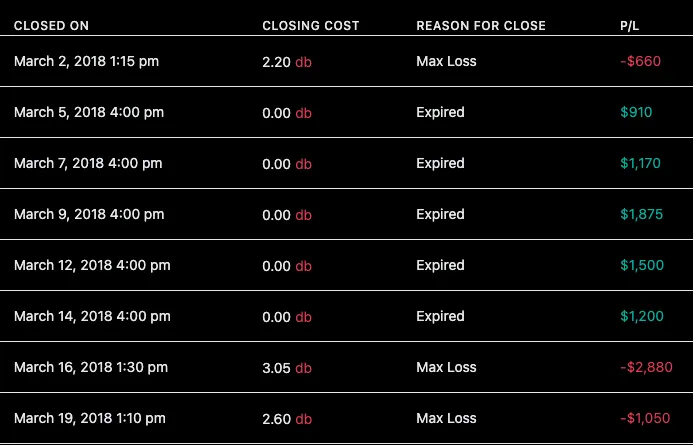
Zero-day strategies live and die on the fills. Option Omega tests them on true 1-minute intervals — and tightens to the second exactly where it matters most.
- 1-minute granularity
- Entries, exits, and indicators all evaluated minute-by-minute across the full session
- Intra-minute stop loss
- More realistic stop-loss modeling with 1-second price checks for SPX and SPY 0DTE strategies
- No more wishful fills
- Mid-price fills with adjustable slippage and commissions, so your results reflect reality
Running long-term strategies?
Get the full picture of how a strategy compounds — and where it would have hurt — across every regime since 2013, from the 2020 crash to 2018's Volmageddon.
- Pro-grade metrics
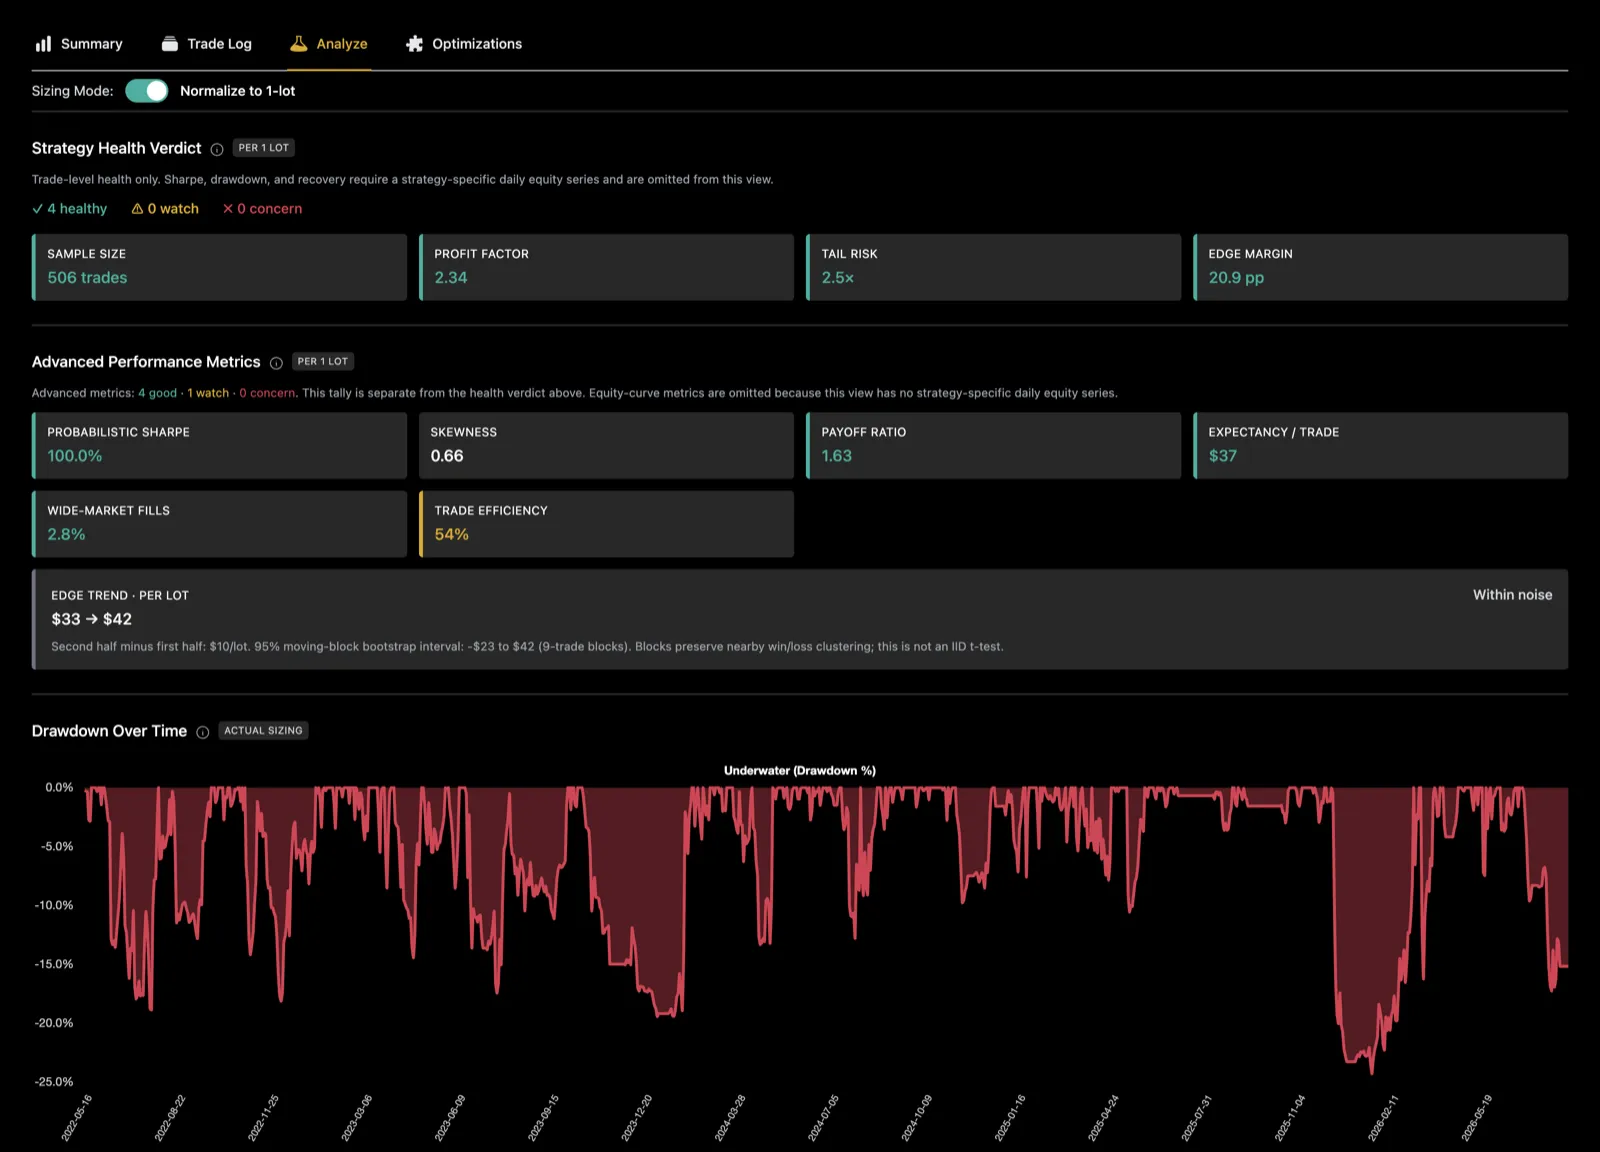
- CAGR, max drawdown, MAR, Sharpe, Sortino, win rate, capture rate, and per-year breakdowns
- Analyze tab
- Monte Carlo simulation, monthly heatmap, drawdown periods, VIX regime tables, position sizing simulator, and a strategy health verdict
- Trade replay
- Scrub any trade minute-by-minute with the option price, underlying, and VIX overlaid
- Fills priced on real market quotes since January 1
- 2013
- 1-minute data for every rule, 1-second 0DTE stop losses on SPX and SPY
- 1-min / 1-sec
- From a simple long call to layered, multi-strategy combo trades
- 8 legs
- Tests per optimization run on Premium
- 500
How it works
From idea to verdict in four steps
Pick your structure
Start from one of 16 prebuilt strategies — iron condor, butterfly, calendar, strangle and more — or build your own with up to 8 legs.
Define your entry rules
Choose strikes by delta, premium, or offset, then layer on filters like VIX, RSI, gaps, opening-range breakouts, and one or many entry times a day.
Set your exits
Add profit targets, stops, trailing stops, delta and time-based exits, leg groups, and re-entry logic — exactly how you'd trade it live.
Run it and see how it behaved
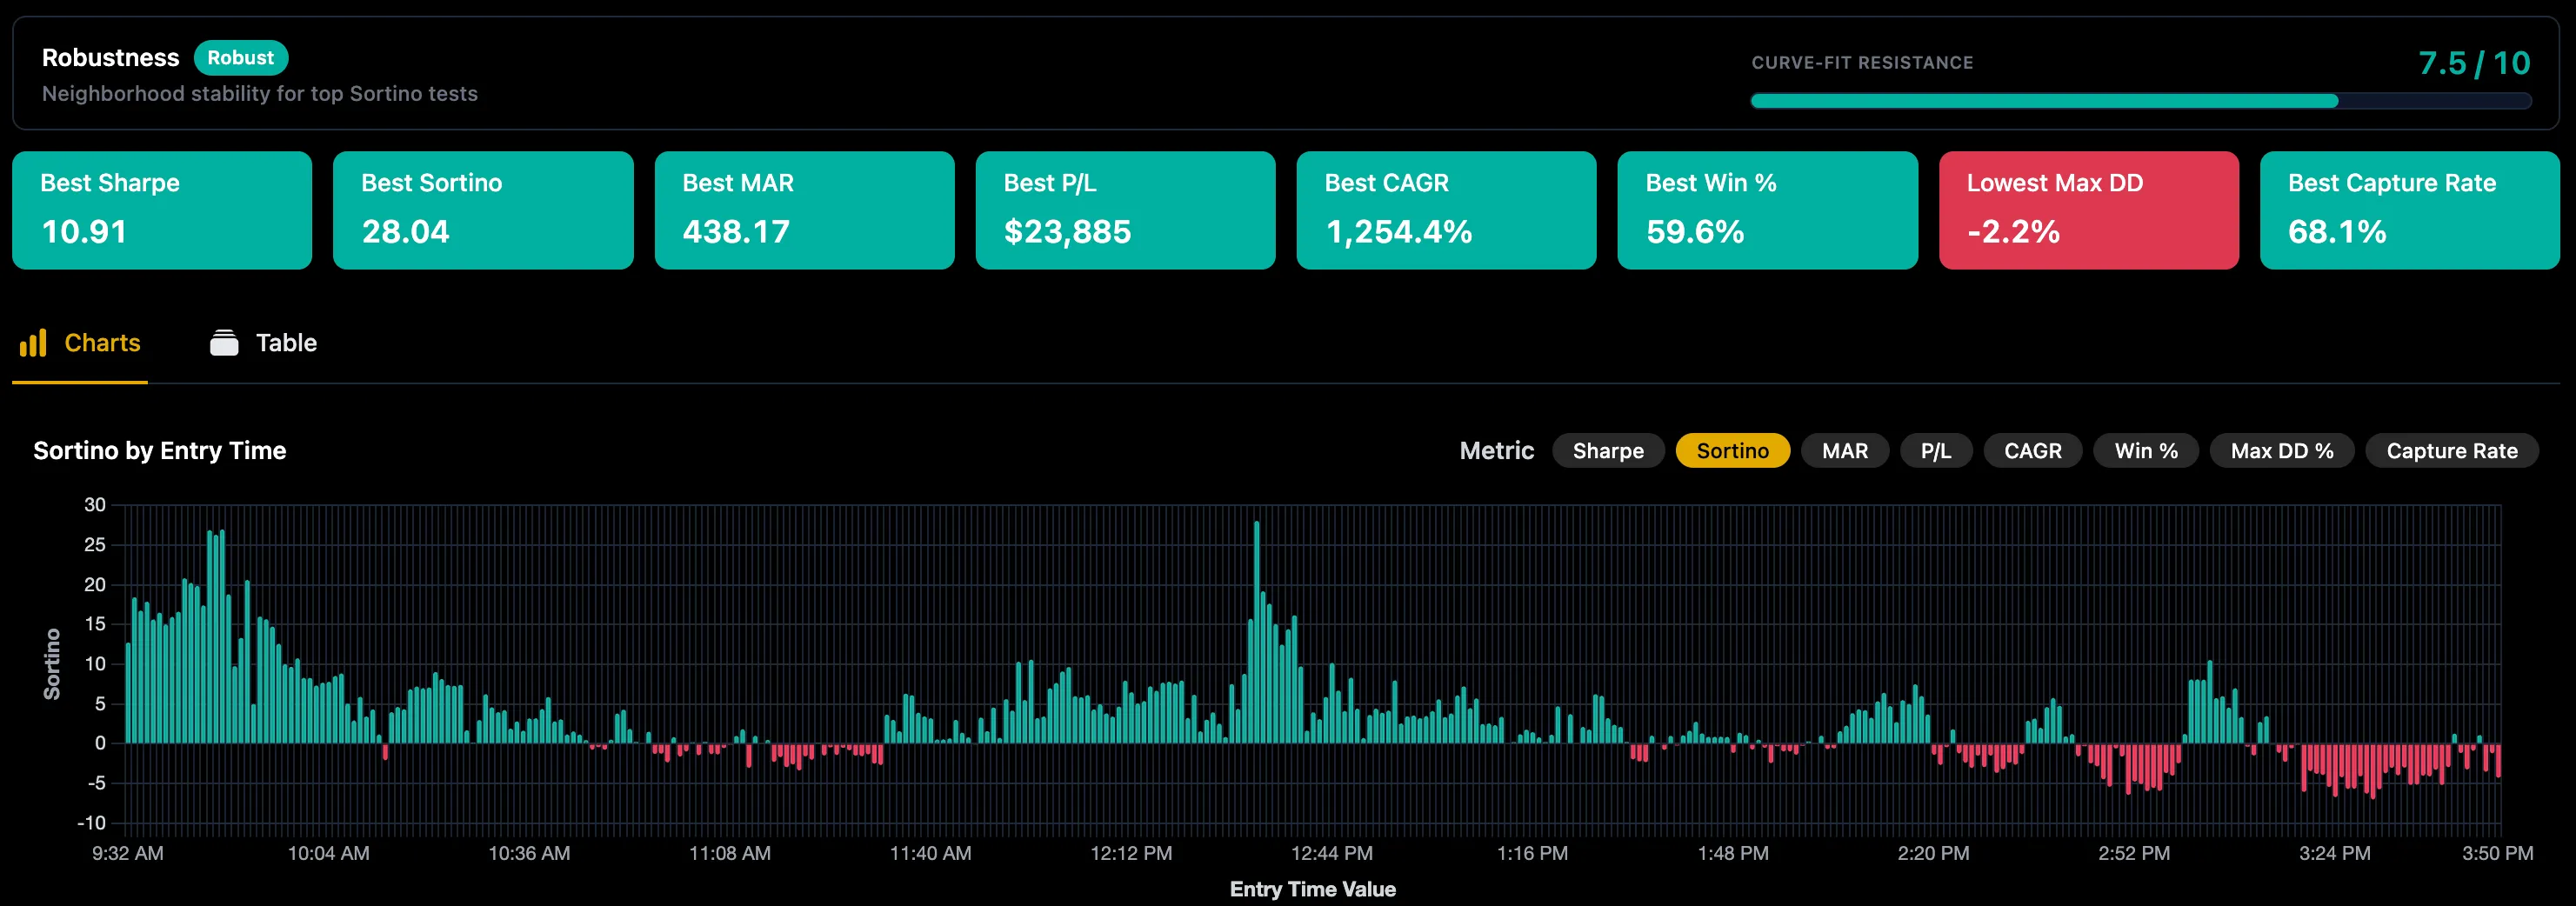
Get CAGR, drawdown, Sharpe, win rate and more in seconds, then replay any trade minute-by-minute to see exactly what happened.
Dial in every last detail
- Flexible strike selection
- Choose strikes based on delta, premium targets, or offset from various reference levels.
- Deep entry filters
- Gate entries on VIX levels and gaps, RSI, SMA/EMA, opening-range breakouts, premium ranges, and DIX/GEX.
- Smart exits
- Profit targets and stops by %, dollar, or closing order — plus trailing stops, delta exits, and time actions.
- Multiple entry scheduling
- Daily, weekly, monthly, or specific dates, with up to 20 intraday entry times per test for multiple entry iron condors (MEIC) and other laddered strategies.
- Leg groups & re-entry
- Single-entry / multi-exit leg groups, automatic re-entry after exits, and per-leg stop monitoring.
- Realistic capital model
- Reg-T margin, percent-of-funds allocation, max open trades, and contract/allocation caps.
- Backtest optimizations
- Sweep strikes, entry times, stop losses, profit targets, and other entry/exit criteria. Up to 10 runs a day of 50 tests on Essential and Plus, 250 a day of 500 tests on Premium.
- Run portfolios
- Combine multiple strategies into a portfolio and test the whole book at once, the way you'd actually trade it.
- Save, tag & share
- Save unlimited tests, organize with tags, export the trade log to CSV, and share a live read-only link.
Your AI chat
Backtest a 0DTE SPX iron condor since 2023. 10-delta shorts, 5-delta wings, 10:00 entry, 50% profit target, 1 contract.
Done. 942 trades. Here's how they did:
- Win rate
- 91.9%
- Profit before fees
- +$5,322
- Average win
- +$97
- Average loss
- -$1,034
It won 9 trades out of 10 and still barely made money. One average loss wiped out more than 10 average wins.
A real backtest, run through our MCP server. Hypothetical results, before fees.
Your AI can nowrun your backtests.
Connect the AI assistant or agent you already use to Option Omega. Describe a strategy in natural language, and our backtester runs it and sends the results straight back to your chat.
- Works with any AI agent or app that supports MCP
- Included with Essential, Plus and Premium
- No code, nothing to install
- Free trials included
Backtesting questions, answered
Where does the data come from?
Historical option prices come from a market data vendor as actual recorded bid/ask — not theoretical Black-Scholes estimates. Trades fill at the mid price by default, and you can add slippage and commissions to model real-world execution. Data covers regular trading hours from January 1, 2013 through yesterday and updates overnight.
Can I really backtest 0DTE strategies accurately?
Yes. All entries and exits are evaluated on 1-minute intervals, and for SPX/SPY 0DTE trades the Intra-Minute Stop Loss (IMSL) checks your stop against per-second prices for more realistic stop-loss modeling.
Which symbols can I test?
SPX (PM-settled), SPY, QQQ, IWM, AAPL, MSFT, AMZN, NVDA, TSLA, TLT, GLD, and IBIT.
Can I backtest a multiple entry iron condor (MEIC)?
Yes. A Multiple Entry Iron Condor, often written MEIC or M.E.I.C., opens a fresh 0DTE condor at several set times through the session. Add up to 20 intraday entry times to one test, set per-leg stops and profit targets, and see how the whole ladder performed on real SPX 1-minute data since 2013.
How many strategies and tests can I run?
Up to 1,000 backtests a day on Essential and Plus and 4,000 on Premium (250 during a free trial), and you can save and tag as many as you want. Run multiple strategies together in a portfolio, where each strategy counts as one backtest, and use optimizations to sweep variations in batches (10 a day of 50 tests on Essential and Plus, 250 a day of 500 tests on Premium).
Can I share my results?
Yes — every backtest can be shared with a read-only link that stays live and updates as the underlying data updates. Great for comparing notes in Discord or with a trading group.
Can I run backtests from ChatGPT, Claude or another AI agent?
Yes. Essential, Plus and Premium include our MCP server, which lets AI agents like Claude and ChatGPT backtest natural language strategies. Describe the trade in your own words, and the agent sets up and runs the backtest, optimizer or portfolio. The results come from this same backtester.
Stop guessing. Start testing.
Build your first strategy and run it against more than a decade of real market data in the next five minutes.